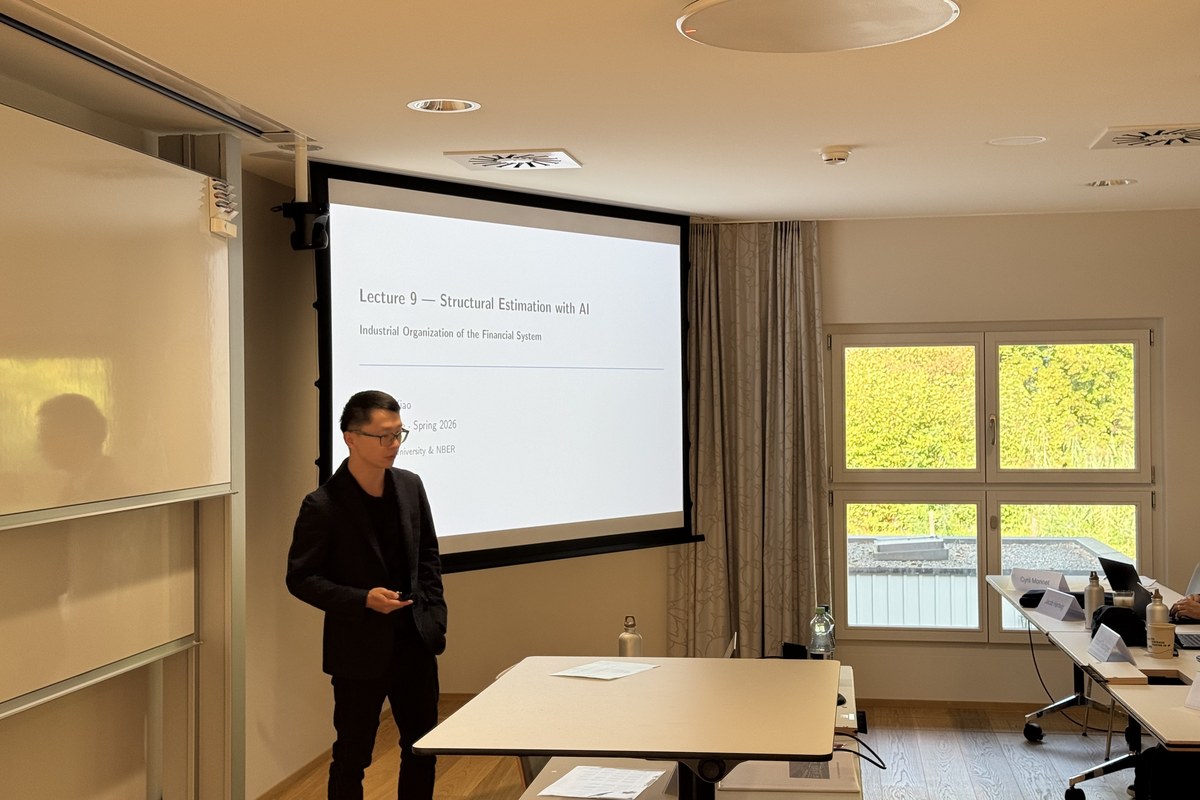
The course brought together industrial organization and finance to study how banks, nonbank financial institutions, asset managers, insurers, and regulators behave when they have market power, face constraints, and respond strategically to policy changes.
#GerzenseeInsights "Industrial Organization of the Financial System"
3 min read
-
Some Financial Questions Cannot Be Answered From Past Data Alone
A great deal can be learned from studying what happened after a policy change or a financial shock. But many of the most important questions in finance are about situations that have not yet happened. What would happen if a central bank introduced a digital currency? How would lending change if a new capital rule were adopted? What would monetary policy look like in a world without money market funds?
These questions require more than measuring past correlations. They require a model of how households, banks, funds, and firms would change their choices once the environment changes. A recurring lesson of the course was that structural models are useful precisely when the policy question concerns a counterfactual: a world that is relevant for policy, but not directly visible in the data.
-
Basic Textbook Models Miss Important Facts About Financial Markets
Many standard models start from a useful simplification: financial markets are competitive, prices adjust smoothly, and investors can buy or sell assets without changing prices much. The course began by showing why this benchmark is often not enough. Deposit rates do not move one-for-one with central-bank policy rates. Long-term bond yields sometimes react much more strongly to short-rate surprises than simple models predict. Nonbank credit markets can become fragile even when the institutions involved are not traditional banks.
Industrial organization helps explain these facts because financial intermediaries are not passive. Banks compete for depositors, but not all depositors care equally about interest rates. Asset managers buy and sell securities on behalf of investors who may withdraw quickly. Insurers and pension funds have long-term commitments that shape their demand for assets. Regulators and regulated firms also respond to incentives. Once these institutions are modeled as strategic actors, several puzzling facts become easier to understand.
-
Market Power Changes How Monetary Policy Reaches Households and Firms
Monetary policy does not move directly from a central bank's policy rate to the borrowing conditions faced by households and firms. It passes through banks and other financial institutions. If banks have market power in deposit markets, they may not raise deposit rates fully when policy rates rise. Some savers then move toward money market funds or other alternatives, while less rate-sensitive customers remain with commercial banks.
This affects lending. When deposits leave banks, banks may have to replace them with more expensive funding. As a result, deposit-market power can influence how strongly policy rates affect loan supply. The course also showed why dynamics matter. Banks do not make decisions one period at a time: today's profits affect tomorrow's capital, long-term loans remain on balance sheets, and regulatory constraints can bind in the future. In some settings, very low interest rates can even weaken bank lending by eroding the value of the deposit franchise that supports bank capital.
-
Financial Stability Depends on Who Holds the Asset
Financial fragility is often associated with banks, leverage, and capital shortages. The course showed that fragility can also arise outside the banking system. Mutual funds and exchange-traded funds may hold relatively illiquid bonds while allowing investors to withdraw quickly. If investors withdraw during a stress episode, funds may sell assets, prices may fall, and further withdrawals may follow.
This means that the systemic importance of an asset depends not only on its own risk, but also on who holds it. A seemingly safe or liquid bond can become central to a crisis if it is held by investors who are likely to sell first. Conversely, institutions such as insurers can stabilize markets when they have long horizons and are willing to buy during stress. For policymakers, this shifts attention from the asset alone to the structure of ownership and the incentives of the investors holding it.
-
Regulation Is Part of the Economic System, Not Just a Background Rule
The course also studied regulation using the same economic logic. Rules often create thresholds: a bank above a certain size faces additional requirements; a public employee above a salary cutoff may face restrictions on future private-sector employment; a firm above a listing threshold may face new disclosure obligations. When people or firms bunch just below such cutoffs, their behavior reveals how costly the rule is to them.
This revealed-preference approach can be especially useful because regulated firms and employees may have incentives to overstate or understate costs when asked directly. By studying what they do, rather than only what they say, researchers can estimate the hidden costs of regulation and the incentives created by legal thresholds. The broader lesson is that financial regulation is not imposed on a fixed world. It changes the choices of the people and institutions it governs.
Selected References:
- Alvero, A., Ando, S., and Xiao, K. (2023). "Watch What They Do, Not What They Say: Estimating Regulatory Costs from Revealed Preferences." Review of Financial Studies, 36(6), 2224-2273
- Darmouni, O., Siani, K. Y., and Xiao, K. "Nonbank Fragility in Credit Markets: Evidence from a Two-Layer Asset Demand System." Forthcoming, Journal of Finance
- Fang, C., and Xiao, K. (2025). "What Do $40 Trillion of Portfolio Holdings Say about Monetary Policy Transmission?" Working paper
- Kalmenovitz, J., Vij, S., and Xiao, K. "Closing the Revolving Door." Forthcoming, Journal of Finance
- Wang, Y., Whited, T. M., Wu, Y., and Xiao, K. (2022). "Bank Market Power and Monetary Policy Transmission: Evidence from a Structural Estimation." Journal of Finance, 77(4), 2093-2141
- Whited, T. M., Wu, Y., and Xiao, K. (2023). "Will Central Bank Digital Currency Disintermediate Banks?" Working paper
- Xiao, K. (2020). "Monetary Transmission through Shadow Banks." Review of Financial Studies, 33(4), 2379-2420
This summary was compiled by Philip Coyle. Philip is postdoctoral research associate and academic assistant at the Study Center Gerzensee and a PhD student at the University of Bern.